In New York City, your take-home pay is what remains after a four-tier tax stack: federal income tax (10%–37%), New York State tax (4%–10.9%), NYC municipal tax (3.078%–3.876%), and FICA (7.65%). On an $85,000 gross salary in 2026, a single NYC resident takes home roughly $61,720 annually or $2,374 bi-weekly—yielding an effective tax rate of 27.4%.
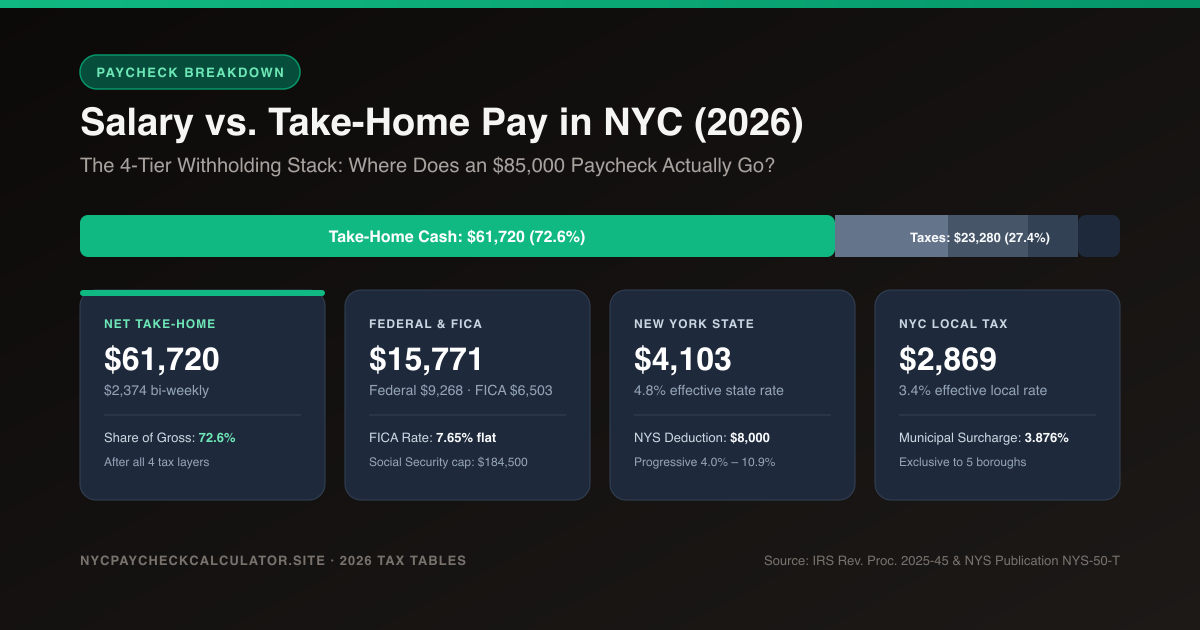
The NYC Four-Tier Tax Stack: Why Local Paychecks Shrink Faster
An offer letter quotes gross salary—the total contractual amount your employer agrees to disburse across the year. Take-home pay (or net pay) is the liquid cash that actually clears into your checking account on payday. In New York City, the disparity between gross and net income is among the widest of any metropolitan region in the United States.
While workers in Dallas, Miami, or Seattle navigate federal taxes and FICA alone, an NYC resident shoulders four separate statutory withholding layers:
10% to 37% Progressive
Governed by IRS progressive brackets. Uses the 2026 standard deduction ($15,700 for single filers; $31,400 married filing jointly) before tax rates apply.
4.0% to 10.9% Progressive
Administered by the NYS Department of Taxation and Finance. Applies state standard deductions ($8,000 single) and progressive marginal brackets.
3.078% to 3.876% Progressive
Exclusive to residents of Manhattan, Brooklyn, Queens, the Bronx, and Staten Island. Top rate of 3.876% applies to taxable income over $50,000.
7.65% Flat (6.2% + 1.45%)
Social Security tax (6.2% up to the $184,500 wage base) and Medicare tax (1.45% on all earnings, plus 0.9% over $200k).
Where Does an $85,000 NYC Salary Actually Go?
Consider a typical full-time NYC resident earning an $85,000 base salary, filing as single with 26 bi-weekly pay periods and taking standard deductions. Here is the exact annual allocation of that paycheck:
2026 Annual Gross Split: $85,000 Base Salary
- Take-Home (72.6%)$61,775
- Federal Tax (10.9%)$9,870
- NY State (4.8%)$3,993
- NYC City Tax (3.4%)$2,860
- FICA (7.65%)$6,503
On this $85,000 gross salary, the employee pays $9,268 in federal income tax, $4,103 in New York State income tax, $2,869 in New York City resident income tax, and $6,503 in FICA taxes. Total statutory deductions equal $23,280 (27.4% of earnings), leaving an annual take-home pay of $61,720 ($2,373.85 per bi-weekly check).
NYC Take-Home Pay Across Benchmark Salaries (2026)
Because federal, state, and city income tax systems are all progressive, effective tax rates climb non-linearly. The table below demonstrates how take-home percentages shift from entry-level to executive salaries:
| Gross Salary | Federal Tax | NY State Tax | NYC Local Tax | FICA Tax | Bi-Weekly Net | Annual Net | Effective Rate |
|---|---|---|---|---|---|---|---|
| $50,000 | $3,820 | $2,103 | $1,508 | $3,825 | $1,490.17 | $38,744 | 22.5% |
| $85,000 | $9,870 | $3,993 | $2,860 | $6,503 | $2,375.95 | $61,775 | 27.3% |
| $150,000 | $24,734 | $7,810 | $5,379 | $11,475 | $3,869.31 | $100,602 | 32.9% |
| $250,000 | $51,304 | $13,962 | $9,255 | $15,514 | $6,152.48 | $159,964 | 36.0% |
Note: Figures represent single filers taking 2026 standard deductions with zero pre-tax contributions. For other income tiers, explore our complete NYC salary guide or calculate your exact check using the paycheck methodology. At $250,000, Social Security caps at $184,500 ($11,439 max), while Additional Medicare Tax (0.9%) applies above $200,000.
Why Your Top Tax Bracket Is Not Your Tax Rate
A persistent myth among New York employees is that a raise or year-end payout can cause take-home pay to decrease by pushing them into a “higher tax bracket.” (You can test supplemental rate withholding with our NYC bonus calculator). In the United States tax code, tax brackets are marginal, not flat.
For example, if your income rises from $95,000 into the 24% federal tax bracket, only the dollars earned above the bracket threshold are taxed at 24%. Every dollar below that threshold is taxed at 0% (standard deduction), 10%, 12%, and 22%. What dictates your real take-home pay is your effective tax rate (total tax liability divided by gross earnings), which always grows predictably and smoothly.
Marginal vs. Effective Rate Comparison ($85,000 Single Filer)
- Marginal Top Bracket: 22% Federal + 5.5% NY State + 3.876% NYC = 31.38% marginal tax rate on your next earned dollar.
- Effective Combined Rate: 10.9% Federal + 4.8% NY State + 3.4% NYC + 7.65% FICA = 27.4% effective tax rate on total gross salary.
How Pre-Tax Deductions Save More Cash in New York City
Because NYC residents pay federal, state, and city income taxes simultaneously, pre-tax payroll deductions generate a higher cash return than almost anywhere else in the nation. Every dollar allocated to an eligible pre-tax vehicle bypasses all three income tax systems:
Traditional 401(k) / 403(b)
2026 IRS contribution limit is $23,500. A $10,000 contribution reduces NYC, NYS, and federal income taxes by up to $3,200.
HSA & Healthcare FSA
Pre-tax payroll deductions for health spending accounts bypass federal, state, city taxes, AND FICA payroll taxes.
Transit & Parking Passes
Eligible transit and subway benefits allow up to $315/month in pre-tax payroll deductions under NYC Commuter Benefits Law.
Why Does Your Actual Paycheck Differ from Online Calculators?
Online paycheck calculators model statutory annual tax liability divided across pay periods under standard baseline assumptions. If your employer pay stub shows a different net deposit, the variance is almost always driven by one of the following factors:
1. Form W-4 and Form IT-2104 Withholding Elections
If you elected extra withholding (W-4 Line 4c), claimed child tax credits (Step 3), or adjusted New York State withholding allowances on Form IT-2104, your employer will withhold amounts tailored to your specific return.
2. Medical, Dental, and Vision Insurance Premiums
Employer group health insurance premiums deducted under Section 125 cafeteria plans reduce gross pay before taxes are calculated, lowering both taxable wages and net pay.
3. Union Dues, Pensions & Mandatory Contributions
Public sector employees (such as NYC DOE teachers or municipal civil servants) contribute between 3% and 6% of gross pay to the Teachers’ Retirement System (TRS) or NYCERS, which alters income-tax withholdings.
Frequently Asked Questions: NYC Take-Home Pay
Common questions about NYC paycheck taxes, deductions, and withholding rules.
What is the difference between gross salary and take-home pay in NYC?+−
Gross salary is the total annual compensation agreed to by your employer before any withholdings. Take-home pay (also known as net pay) is the cash deposited into your bank account after mandatory federal income taxes, New York State taxes, New York City municipal taxes, and FICA (Social Security and Medicare), along with voluntary pre-tax benefit deductions.
How much tax is withheld from an average NYC paycheck in 2026?+−
For an average single earner in New York City making between $65,000 and $95,000, total tax deductions typically consume between 25% and 29% of gross wages. This includes roughly 10%–12% for federal income tax, 4.5%–5.5% for NY State tax, 3.5%–3.8% for NYC resident tax, and 7.65% for FICA.
Does New York City tax nonresidents who commute into the five boroughs?+−
No. Standard private-sector commuters residing in New Jersey, Connecticut, Westchester, or Long Island are exempt from the NYC personal income tax. However, all New York City municipal employees (such as police officers, firefighters, and DOE staff) must pay an equivalent payment under Section 1127 of the NYC Charter even if they reside outside the city.
How does a 401(k) contribution increase your paycheck efficiency in NYC?+−
Traditional 401(k) contributions are deducted pre-tax, meaning they reduce your taxable wage base for federal, New York State, and NYC personal income taxes simultaneously. In NYC, every dollar contributed to a traditional 401(k) saves between 30¢ and 35¢ in immediate income taxes for middle-class filers, although FICA payroll taxes still apply to gross wages.
Why does getting a raise not decrease your net take-home pay?+−
Federal, New York State, and NYC income tax brackets are strictly marginal, not retroactive. Moving into a higher bracket only subjects the dollars earned above that bracket threshold to the higher tax rate; all income earned below the threshold remains taxed at the lower progressive rates.
What is the 2026 Social Security wage cap and how does it affect take-home pay?+−
For the 2026 tax year, the Social Security Administration has set the maximum taxable earnings limit at $184,500. Once year-to-date gross wages exceed $184,500, the 6.2% Social Security deduction stops completely for the remainder of the calendar year, resulting in a noticeable paycheck boost for high earners.
What is the Additional Medicare Tax for NYC workers?+−
Under the Affordable Care Act, individual filers earning over $200,000 (or $250,000 for married couples filing jointly) are subject to an Additional Medicare Tax of 0.9% on wages exceeding the threshold, lifting the marginal Medicare withholding rate from 1.45% to 2.35%.
Why does my actual pay stub differ from an online paycheck calculator?+−
Online calculators project annual statutory tax liability divided evenly across pay periods using standard deductions. Real employer pay stubs reflect Form W-4 and IT-2104 elections, cafeteria plan health insurance premiums, commuter transit passes, union dues, flexible spending accounts, and supplemental withholding on bonuses.
How does pay frequency (bi-weekly vs semi-monthly) change take-home pay?+−
Pay frequency changes the deposit amount per paycheck, but does not alter your annual net take-home pay or tax liability. Bi-weekly employees receive 26 paychecks per year (including two 'three-paycheck months'), while semi-monthly employees receive 24 larger paychecks twice per month.
Are bonuses taxed at a higher rate than regular salary in New York?+−
At the withholding stage, employers often withhold bonuses at supplemental flat rates (22% federal plus New York State supplemental withholding of approximately 9.9% for high bonuses or standard withholding tables). However, when you file your annual tax return, bonuses are combined with regular wages and taxed at your exact marginal income tax bracket, with any overwithheld taxes refunded.
Official Regulatory Sources
- IRS Revenue Procedure 2025-45: 2026 Federal Tax Rates & Standard Deductions
- New York State Dept of Taxation & Finance: Publication NYS-50-T (2026 Withholding Tables)
- Social Security Administration: 2026 Social Security Wage Base ($184,500)
- NYC Department of Finance: Personal Income Tax Rates and Tables